|
|

| Home |  |
Overview
|
|
This is Barloworld
|
|
Leadership review
|
|
Strategic framework
|
|
Financial returns
|
|
Governance review
|
|
Assurances
|
| Currently viewing: Finance director's report / Next: Group executive: Human resources, strategy and sustainability report |
Finance director's reportKey highlights
Operating profit rose by 16% to R3 830 million with operation margin increasing to 6.2%
Revenue for the year increased by 4% to R62.1 billion, mainly
due to increased revenues in Equipment southern Africa
(R1.8 billion) in particular the Extended Mining Product Range
(EMPR) and Automotive and Logistics Earnings before interest, taxation, depreciation and amortisation (EBITDA) increased by 14% to R6 170 million with depreciation and amortisation increasing by 13%. Operating profit rose by 16% to R3 830 million with
the operating margin increasing to 6.2%. The strong
operating results generated in Equipment southern Africa
(R1 968 million) and Russia (R429 million) made up for the
operating loss of R168 million (€11.7 million) incurred in
Equipment Iberia, which included restructure costs of
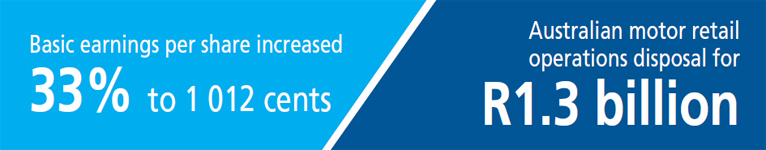
The Automotive and Logistics division produced another strong performance with all business units performing well, increasing operating profit by 24% to R1 644 million. This was after making provision for the exposure arising from the Ellerines Holdings business rescue. The total negative fair value adjustments on financial instruments of R156 million (2013: R47 million) mainly relate to the cost of forward points on foreign exchange contracts in Equipment southern Africa and Handling South Africa. Finance costs increased by R117 million to R1 117 million. The increase is mainly due to higher average debt levels, arising from increased average working capital levels for the year, increased fleet leasing and rental fleets and capex relating to investment in the logistics business, further impacted by higher interest rates. We remitted £60 million of the proceeds on sale of the Australian operations back to South Africa at the end of September in order to reduce local borrowing costs in the coming year. Exceptional items of R66 million (net charge) mainly comprise the impairments of goodwill in the Logistics Sea Air Transport business (R208 million), and intangible assets and other assets in the Logistics Supply Chain Management business related to the Ellerines contract (R76 million). This was offset by profits from foreign currency translation reserves of R97 million realised on disposals of offshore businesses in handling and logistics, profits on disposal of investments (R64 million), and a profit on sale of property of R77 million. Taxation charge for the year was R837 million. This included further impairment of the Spanish deferred tax asset of €3 million (R42 million). The effective taxation rate (excluding prior year taxation and taxation on exceptional items) was 34.1% (2013: 31.8%). The effective rate was negatively impacted by the unrelieved tax losses in Equipment Iberia and deferred tax arising on exchange movements in foreign subsidiaries. Income from associates and joint ventures increased by 17% to R217 million (2013: R185 million) again driven by a strong performance from Equipment joint ventures. The non-controlling interest in the current year’s earnings includes dividends of R44 million paid to participants of the BEE transaction, with the balance relating to the minorities in our NMI/DSM and Transport subsidiaries. Headline earnings per share (HEPS) from continuing operations increased by 10% to 857 cents (2013: 780 cents) and total HEPS (including discontinued operations) increased by 8% to 883 cents (2013: 821 cents). Basic earnings per share (EPS) (including discontinued operations) of 1 012 cents is 33% higher than the prior year due to the exceptional profit of R374 million generated on the disposal of the Australian motor retail operations. Cash flow Cash generated from operations decreased to R3.0 billion (2013: R4.3 billion generated). Activity levels in the second half resulted in an increase in working capital for the year of R470 million (2013: R539 million decrease) which includes a funding payment to the UK defined benefit pension scheme of £15.2 million (R0.3 billion). The increased investment in fleet leasing assets was mainly due to the increased Equipment SA long-term rental fleet. Summarised cash flow statement
Net cash applied in the net investment of property, plant and equipment together with subsidiaries and intangibles of R1.4 billion was largely offset by the proceeds on disposal of Motor Retail Australia of R1.3 billion. This contributed to a net inflow of funds for the year of R145 million compared to an inflow of R660 million last year, which represented a significant improvement on the cash outflow of R3.9 billion reported at the interim. Financial position and debt Total assets employed in the group increased by R3.4 billion to R44 billion. The increase was driven by the weaker rand (R1.3 billion) and an increase in rental and leasing assets, as well as the acquisition of property, plant and equipment during the year. Total interest-bearing debt at 30 September 2014 increased to R11.3 billion (2013: R10.3 billion) while cash and cash equivalents increased to R4.2 billion (2013: R2.7 billion). Net debt reduced in the second half as a result of the seasonal decrease in working capital, and was positively impacted by the receipt of the proceeds from the sale of Motor Retail Australia. Net interest-bearing debt at 30 September 2014 of R7.2 billion was R404 million down on the prior year of R7.6 billion. Debt
In December, the company issued three senior unsecured notes totalling R1 541 million under the South African Domestic Medium-Term Note programme. R714 million matures in 2019 financial year and R827 million in 2021 financial year. In addition, a R700 million bank term facility was extended for a further five years. During the second half the group concluded a five-year revolving bank credit facility of R1 billion, while Barloworld Transport finalised banking facilities of R561 million. The funds raised have been utilised to fund short-term working capital requirements and to improve the maturity profile of group debt. In South Africa, short-term debt includes commercial paper totalling R1.0 billion (September 2013: R1.2 billion). While this market has remained liquid, spreads have been negatively impacted by interest rate uncertainty. We expect to maintain our participation in this market. Cash balances of R4.2 billion are available to meet short-term commitments. The group has short-term borrowings at 30 September 2014 of R4 395 million, committed unutilised borrowing facilities of R6 102 million and further uncommitted facilities of R2 280 million. Fitch Ratings downgraded the company’s long-term credit rating to A+(zaf) (stable outlook) following the annual credit review in February 2014. While this had a marginal impact on the cost of short-term commercial paper funding, we have not experienced any impact on our cost of long-term borrowings. The group debt to equity ratio at 30 September 2014 was 64.7% (September 2013: 64.0%), while group net debt to equity was 40.9% (September 2013: 47.5%). Gearing in the three segments are as follows:
The weaker rand resulted in an increase of R744 million in shareholders’ funds (2013: R800 million increase). Accounting policies The annual financial statements have been prepared in accordance with International Financial Reporting Standards (IFRS) as issued by the International Accounting Standards Board (IASB). The basis is consistent with the prior year except for the adoption of new amended standards and new interpretations which have been outlined in note 33 of the Group Annual Financial Statements. Barloworld’s results for the year ended 30 September 2013 were restated to reflect changes in accounting policies as well as the disclosure of the Australian motor retail interests as discontinued operations. Changes in accounting policy resulting from applying IAS19 (revised) Employee Benefits and IFRS 10 Consolidated Financial Statements, resulted in a restatement of prior year results on a comparable basis. Dividends Dividends totalling 320 cents per share were declared in respect of this year’s earnings (2013: 291 cents).Of the issued shares of 231.3 million, only 227.7 million are entitled to receive dividends. The majority of shares not entitled to dividends relate to the Black Managers Trust (BMT) and Education Trust (ET). The dividends declared this year are covered 2.6 times by headline earnings (2013: 2.6 times). Going forward The group return on net operating assets increased from 18% in 2013 to 18.8% in the current year driven by the strong operating performances in Equipment southern Africa and the Automotive and Logistics division. The group continues to deploy capital into higher returning businesses, which together with a projected return to profitability in Equipment Iberia, should further contribute to improved returns in 2015. Donald Wilson |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
|